Net-to-Gross Paystub Calculator: How to Gross Up Bonuses and Fringe Benefits in Spreadsheets
Key Takeaways
- ✓The Net Bonus Dilemma: Promising an employee an exact $1,000 net bonus means the employer must absorb all statutory tax liabilities. Entering $1,000 as gross earnings shrinks take-home pay to ~$650–$700 after federal, state, and FICA deductions, causing immense employee dissatisfaction.
- ✓The Exact Algebraic Gross-Up Formula: Calculating gross compensation from a target net amount requires solving
Gross = Net Bonus / (1 - Total Combined Tax Rate). When employees cross statutory thresholds (such as the Social Security wage base cap), piecewise conditional math must be applied. - ✓Federal & State Supplemental Tax Rules: Under IRS Publication 15-T, supplemental wages under $1,000,000 are subject to an optional flat 22% federal withholding (37% over $1M), combined with mandatory 6.2% Social Security, 1.45% Medicare, and state-specific supplemental tax rates.
- ✓Fringe Benefits & Relocation Gross-Ups: Non-cash taxable awards, relocation stipends, executive gift cards, and gym allowances must be grossed up on payroll statements so recipients incur zero out-of-pocket tax burdens.
- ✓Local Batch Payslip Generation: By combining dynamic Excel gross-up formulas with PayslipGen, employers can batch-generate itemized, password-encrypted PDF payslips showing clear gross earnings, tax lines, and exact net disbursements in seconds without SaaS fees.
Rewarding your team with a cash bonus, holiday incentive, or milestone recognition award is one of the most effective ways to boost morale and foster employee loyalty. When an executive or business owner tells a top-performing employee, "We are awarding you a $1,000 performance bonus," the employee expects to see exactly $1,000.00 deposited into their bank account.
However, when standard payroll runs without reverse tax planning, the reality is starkly disappointing. The employee opens their bank app on payday only to discover a deposit of $683.50. The remaining $316.50 was consumed by federal supplemental income taxes, state withholdings, Social Security, and Medicare. Instead of feeling recognized and energized, the employee feels shortchanged—wondering why their promised $1,000 bonus vanished into government coffers.
To deliver a guaranteed net cash amount—or to cover the taxable value of non-cash fringe benefits like relocation packages, executive travel perks, and performance prizes—companies must perform a Net-to-Gross Calculation, commonly known in payroll accounting as a "Gross-Up."
While enterprise payroll bureaus charge exorbitant off-cycle fees or force you into confusing black-box cloud calculators, mastering reverse tax mathematics directly in Microsoft Excel or Google Sheets gives you complete financial control. In this definitive guide, we will break down the exact algebraic equations, federal and state supplemental withholding rules, FICA wage base caps, fringe benefit tax strategies, and show you how to generate professional, itemized gross-up payslips in bulk using PayslipGen.
Try Our Interactive Demo Instantly
Want to see how an offline-capable, client-side payslip generator works in practice? Try our brand-new interactive demo right in your browser. Upload a sample CSV, map your columns, and generate beautifully designed PDF payslips—with zero data ever being transmitted to our servers.
Launch Free Demo NowChapter 1: The Anatomy of a Gross-Up - Understanding the Problem
In conventional payroll processing, compensation calculations flow in one direction: Gross-to-Net. You begin with the employee's contractual gross wage, calculate statutory pre-tax deductions, subtract federal, state, and local income tax withholdings, deduct employee-share FICA taxes, and arrive at the final Net Take-Home Pay.
When an employer commits to delivering a specific net payout, this calculation must be run in reverse. The employer agrees to pay the employee's share of payroll and income taxes on that specific disbursement on top of the bonus itself.
The Compounding Tax Trap
A common mistake made by inexperienced payroll clerks is calculating taxes on the target net amount and simply adding that tax figure to the bonus. For example, if an employee is subject to a 30% aggregate tax rate and wants a $1,000 net bonus, the clerk adds 30% of $1,000 ($300) to create a gross bonus of $1,300.
When payroll runs on $1,300, the 30% tax rate applies to the new gross amount:
Taxes Withheld (30% of $1,300) = $390.00
Actual Net Pay = $1,300.00 - $390.00 = $910.00 (Shortfall of $90.00!)
Because taxes are levied on the final gross disbursement, every dollar the employer adds to cover taxes is itself subject to taxation. This circular dependency requires true algebraic division rather than basic percentage addition.
| Scenario | Stated Gross | Total Taxes (30%) | Employee Net Received | Outcome |
|---|---|---|---|---|
| No Gross-Up | $1,000.00 | $300.00 | $700.00 | Employee loses $300 to withholdings |
| Flawed Addition Method | $1,300.00 | $390.00 | $910.00 | Calculation error leaves $90 shortfall |
| True Algebraic Gross-Up | $1,428.57 | $428.57 | $1,000.00 | Exact promised net delivered |
Chapter 2: The Exact Algebraic Formula for Net-to-Gross Calculations
To determine the exact gross amount required to yield a target net figure, we derive the formula using fundamental linear algebra.
The Algebraic Derivation
Let:
- T_fed = Federal Supplemental Withholding Rate (e.g., 22% or 0.22)
- T_state = State Supplemental Withholding Rate (e.g., 6.6% or 0.066)
- T_ss = Social Security Tax Rate (6.2% or 0.062)
- T_med = Medicare Tax Rate (1.45% or 0.0145)
- T_local = Local/City Tax Rate (e.g., 3.876% or 0.03876)
- T_total = Combined Total Tax Rate (T_fed + T_state + T_ss + T_med + T_local)
The fundamental payroll identity states that net pay equals gross pay minus total taxes:
Net = Gross - (Gross × Total Tax Rate)
Net = Gross × (1 - Total Tax Rate)
Solving for Gross (G) by dividing both sides by (1 - Total Tax Rate):
Step-by-Step Numerical Example
Suppose an employer in Ohio wants to give an employee a flat $2,500.00 net bonus. Let's determine the exact gross compensation and each itemized withholding line:
- Federal Supplemental Rate (T_fed): 22.00%
- Social Security Tax (T_ss): 6.20%
- Medicare Tax (T_med): 1.45%
- Ohio State Supplemental Rate (T_state): 3.50%
- City Income Tax (T_local): 2.00%
First, calculate the Combined Tax Rate (T_total):
Next, calculate the Gross-Up Divisor:
Now, calculate the Required Gross Amount:
Let's verify the itemized deductions on the employee's payslip:
- Gross Bonus: $3,855.05
- Federal Withholding (22%): $3,855.05 × 0.22 = $848.11
- Social Security (6.2%): $3,855.05 × 0.062 = $239.01
- Medicare (1.45%): $3,855.05 × 0.0145 = $55.90
- Ohio State Tax (3.5%): $3,855.05 × 0.035 = $134.93
- City Tax (2.0%): $3,855.05 × 0.020 = $77.10
- Total Deductions: $848.11 + $239.01 + $55.90 + $134.93 + $77.10 = $1,355.05
- Net Take-Home Pay: $3,855.05 - $1,355.05 = $2,500.00 (Perfect match!)
Chapter 3: Statutory Federal and State Tax Rules for Supplemental Wages
To implement accurate spreadsheet formulas, HR and payroll professionals must understand how statutory tax authorities classify and regulate bonus payments. Under IRS guidelines, bonuses, commissions, overtime, severance pay, and awards are classified as Supplemental Wages.
1. IRS Supplemental Withholding Guidelines (Publication 15-T)
The Internal Revenue Service provides two methods for withholding federal income tax from supplemental wages:
- The Percentage Method (Flat 22% Rate): If supplemental wages are paid concurrently with regular wages and specified separately (or paid as a standalone off-cycle disbursement), and the employee has federal income tax withheld from regular wages, the employer can withhold a flat 22% on supplemental wages up to $1,000,000 in a calendar year.
- The Over-$1,000,000 Mandatory Supplemental Rate (37%): If an employee receives supplemental wages exceeding $1,000,000 during a single calendar year, the portion exceeding $1,000,000 is subject to mandatory federal withholding at the highest statutory bracket: 37% (or the prevailing top individual tax bracket).
- The Aggregate Method: Supplemental wages are combined with regular wages for the current pay period, and withholding is calculated as if the total were a single regular payment. This method frequently pushes employees into artificially high tax brackets, causing cash-flow friction that is only reconciled when filing annual tax returns.
2. FICA Limits and the Social Security Wage Base Cap
Federal Insurance Contributions Act (FICA) taxes consist of two distinct levies:
- Social Security (OASDI): 6.20% withheld from the employee (and matched 6.20% by the employer) up to the statutory annual wage base limit ($176,100 in 2026). Once an employee's cumulative Year-to-Date (YTD) gross compensation reaches this ceiling, zero Social Security tax is withheld on subsequent earnings.
- Medicare (HI): 1.45% withheld on all gross earnings with no annual limit.
- Additional Medicare Tax:An additional 0.90% is withheld once an employee's compensation exceeds $200,000 in a calendar year ($250,000 for married couples filing jointly). Unlike standard Medicare, the employer does not match this additional 0.90%.
The Social Security Threshold Cliff
When grossing up a bonus for an employee near the wage base cap, a portion of the gross bonus may be subject to the 6.2% Social Security tax, while the remainder is exempt. In Chapter 4, we will look at the piecewise formula that handles this boundary condition without circular references.
3. State Supplemental Tax Withholding Matrix
States enforce vastly different withholding rules on supplemental wages. Some states dictate a mandatory flat supplemental rate, others use progressive withholding tables, and nine states levy zero personal income tax:
| State | Supplemental Withholding Method | Flat Supplemental Rate | Notes & Local Rules |
|---|---|---|---|
| California (CA) | Mandatory Flat Rate | 10.23% (Bonuses) / 6.6% (Other) | Stock options & bonuses use 10.23%; commissions use 6.6% |
| New York (NY) | Optional Flat Rate | 11.70% (or Aggregate) | NYC adds local supplemental withholding (~3.876% to 4.25%) |
| Texas / Florida / Washington / Nevada | No State Income Tax | 0.00% | Only Federal + FICA taxes apply in gross-up divisor |
| Pennsylvania (PA) | Flat Statutory Rate | 3.07% | Philadelphia imposes additional non-resident/resident wage tax |
| Illinois (IL) | Flat Statutory Rate | 4.95% | Applies uniformly to regular and supplemental wages |
| Massachusetts (MA) | Flat Statutory Rate | 5.00% | 4% surtax applies to annual income exceeding $1M |
| Georgia (GA) | Flat Income Tax Rate | 5.39% | Transitioning towards 4.99% flat tax system |
| North Carolina (NC) | Flat Income Tax Rate | 4.50% | Scheduled statutory reductions apply in subsequent tax years |
Chapter 4: Fringe Benefits & Non-Cash Awards Gross-Up Strategies
Gross-up calculations are not limited to cash bonuses. Under IRS Publication 15-B (Employer's Tax Guide to Fringe Benefits), any property, service, or cash equivalent provided to an employee is treated as taxable compensation unless specifically excluded by the Internal Revenue Code.
Common Scenarios Requiring Fringe Benefit Gross-Ups
Relocation & Moving Expenses
Under the Tax Cuts and Jobs Act (TCJA), employer-paid moving reimbursements and direct moving services are 100% taxable to the employee. A $15,000 corporate relocation package can leave an executive with a $5,000 tax bill unless the employer grosses up the benefit.
Prizes, Trips & Incentive Awards
Awarding an all-expenses-paid $6,000 President's Club vacation to top sales performers triggers a taxable event for the fair market value of the trip. Employers gross up the award so winners enjoy the trip without out-of-pocket payroll deductions.
Gift Cards & Spot Awards
IRS regulations strictly state that cash equivalents (such as Amazon, Visa, or department store gift cards) can never qualify as tax-free de minimis fringe benefits, regardless of how small the dollar amount is.
Executive Life Insurance & Car Perks
Group term life insurance coverage exceeding $50,000 (imputed income) and personal use of company-provided vehicles must be recognized on payroll, often with offsetting gross-up allowances.
How Non-Cash Fringe Gross-Ups Differ from Cash Bonuses
In a cash bonus gross-up, the employee receives the target net cash in their bank account. In a non-cash fringe benefit gross-up, the employee has already received the physical benefit (e.g., the airline tickets or moving truck services).
Therefore, on the payslip, the payroll engine must:
- Record the Fair Market Value (FMV) of the fringe benefit in taxable gross earnings.
- Add the calculated Tax Gross-Up Allowance to gross earnings.
- Withhold the total taxes generated by both the benefit and the gross-up allowance.
- Offset the non-cash benefit value as an after-tax deduction so that the net cash disbursement on payday is $0.00 (meaning the employee receives zero cash, but pays zero tax out of pocket).
Chapter 5: Building the Ultimate Excel & Google Sheets Gross-Up Model
Let's build a robust, scalable Excel payroll model that automates net-to-gross calculations for hundreds of employees while accounting for state taxes and the Social Security wage cap.
Master Spreadsheet Schema
Structure your master spreadsheet with the following exact columns:
| Col | Header Name | Sample Value | Formula / Definition |
|---|---|---|---|
| A | Employee_ID | EMP-1042 | Unique Identifier |
| B | Full_Name | Sarah Jenkins | Employee Name |
| C | s.jenkins@acmecorp.com | Recipient email for payslip dispatch | |
| D | YTD_Prior_Gross | $165,000.00 | Cumulative prior gross wages for FICA check |
| E | Target_Net_Bonus | $10,000.00 | Promised take-home bonus amount |
| F | Fed_Supp_Rate | 0.22 | Flat 22% Federal Supplemental Rate |
| G | State_Supp_Rate | 0.066 | State Supplemental Withholding Rate |
| H | Medicare_Rate | 0.0145 | Standard 1.45% Medicare |
| I | Gross_Up_Bonus | $14,586.32 | =ROUND(..., 2) (Formula detailed below) |
| J | Fed_Withholding | $3,208.99 | =ROUND(I2 * F2, 2) |
| K | Social_Security_Tax | $688.20 | =ROUND(MIN(I2, MAX(0, 176100 - D2)) * 0.062, 2) |
| L | Medicare_Tax | $211.50 | =ROUND(I2 * H2, 2) |
| M | State_Withholding | $962.70 | =ROUND(I2 * G2, 2) |
| N | Calculated_Net | $10,000.00 | =I2 - (J2 + K2 + L2 + M2) |
| O | Audit_Variance | $0.00 | =ROUND(N2 - E2, 2) (Must equal $0.00) |
Core Excel Formulas
1. Standard Gross-Up Formula (Under Social Security Cap)
When the employee's cumulative gross earnings (including the bonus) will remain below the annual Social Security limit ($176,100), the standard single-cell formula is:
2. Advanced Piecewise Formula (Handling Social Security Cap Crossing)
If an employee has already earned $165,000, only the first $11,100 ($176,100 - $165,000) of new earnings is subject to Social Security tax (6.2%). Any earnings above $11,100 are subject only to Federal (22%), State (6.6%), and Medicare (1.45%).
The piecewise algebraic equation in Excel is:
This formula eliminates manual recalculations and guarantees exact penny precision for employees at any income level.
Chapter 6: Form W-2 and Employer Payroll Tax Obligations
A common point of confusion among executive leadership and accounting teams is how grossed-up bonus payments are reported on annual tax filings and financial statements.
1. Employee W-2 Reporting
On IRS Form W-2, the employee's reported wages reflect the Grossed-Up Earnings, not the net bonus received:
- Box 1 (Wages, tips, other compensation): Includes the full grossed-up bonus amount ($14,586.32 in our example).
- Box 2 (Federal income tax withheld): Includes the 22% federal tax paid on the employee's behalf ($3,208.99).
- Box 3 & Box 5 (Social Security & Medicare wages): Total subject wages up to applicable statutory limits.
- Box 4 & Box 6 (Social Security & Medicare tax withheld): Total employee-share FICA taxes paid.
- Box 16 & Box 17 (State wages & state income tax withheld): Grossed-up state wage and corresponding tax payment.
2. Employer-Side Payroll Tax Liabilities (True Total Cost)
When budgeting for a net bonus, finance teams must remember that the company is responsible for Employer-Share Payroll Taxes on top of the grossed-up wage:
- Employer Social Security Match: 6.20% on gross wages up to the cap limit.
- Employer Medicare Match: 1.45% on all gross wages (unlimited).
- Federal Unemployment Tax (FUTA): 0.60% on the first $7,000 of annual wages per employee (usually already satisfied earlier in the year).
- State Unemployment Insurance (SUTA): State-determined rate on state-specific wage bases.
Total Employer Cash Outlay for a $1,000 Net Bonus
Chapter 7: Generating Professional Gross-Up Payslips with PayslipGen
Having a spreadsheet with perfect mathematical calculations is only half the battle. Delivering raw Excel rows to employees looks unprofessional, invites confusion regarding withholdings, and exposes confidential payroll formulas.
Employees require a clean, legally structured PDF Payslip that clearly illustrates their gross bonus earnings, itemized tax withholdings paid on their behalf, and the exact net direct deposit amount.
The 4-Step Batch Workflow with PayslipGen
1Export Your Master Gross-Up Spreadsheet
Save your calculated Excel or Google Sheets workbook as a standard .xlsx or .csv file. Ensure column headers clearly differentiate between Gross Bonus, Federal Withholding, Social Security, Medicare, State Tax, and Net Pay.
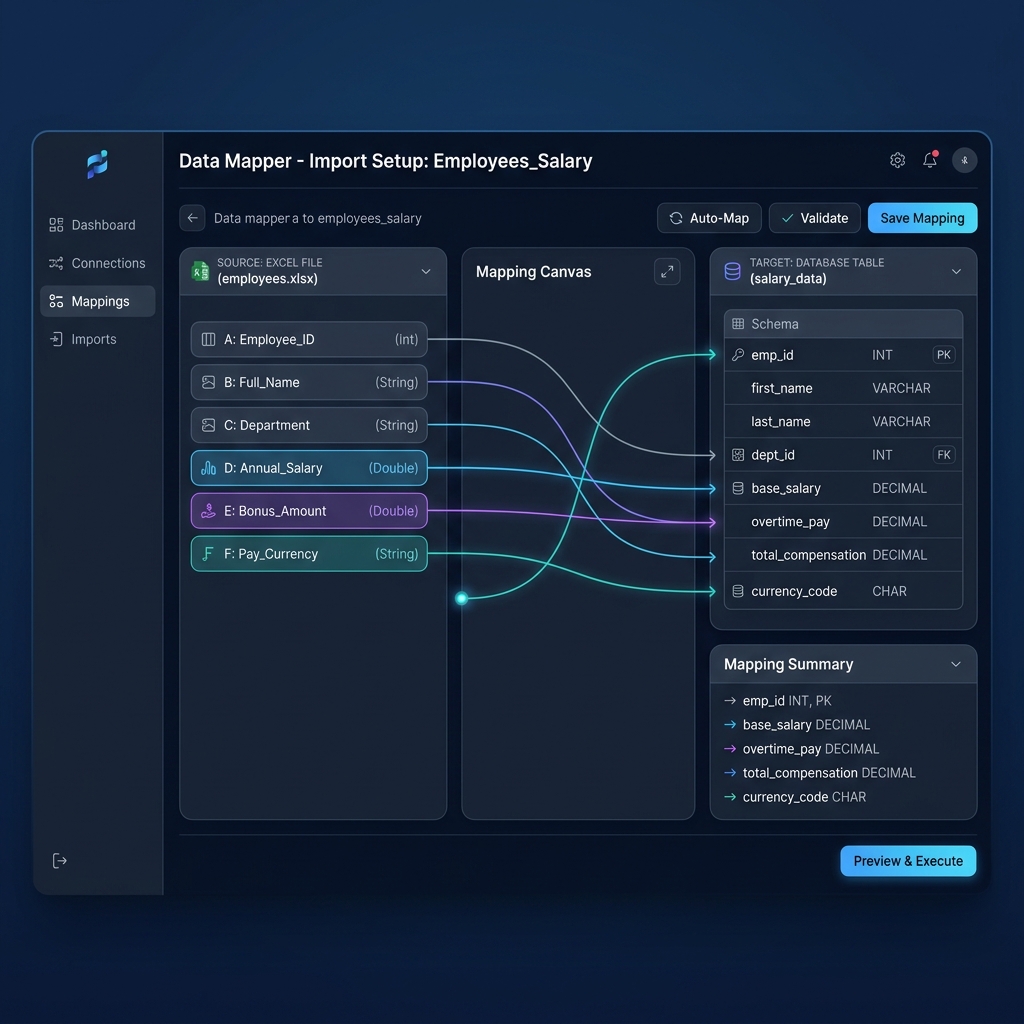
2Import into PayslipGen & Map Data Columns
Open PayslipGen on your Windows or Mac workstation. Select your company template, upload your company logo and digital signature/stamp, and map your spreadsheet columns to the itemized earnings and tax deduction fields.
3Apply Per-Employee AES-256 PDF Password Encryption
Protect confidential employee earnings and SSN data by enabling automated PDF encryption. PayslipGen dynamically generates a unique password for each PDF (such as Date of Birth YYYYMMDD or Last 4 digits of SSN), ensuring complete privacy compliance.
4Batch Render and Dispatch via Custom SMTP
Click "Generate & Send." PayslipGen processes the entire batch locally on your machine in seconds, attaching personalized PDF payslips to customized email messages sent through your own corporate SMTP (Google Workspace, Microsoft 365, Amazon SES, or SendGrid).
Chapter 8: Solution Comparison Matrix
How does local spreadsheet automation with PayslipGen compare against manual calculation or high-cost cloud payroll providers?
| Feature / Capability | Manual Reverse Math | Cloud SaaS (Gusto/ADP) | Excel + PayslipGen |
|---|---|---|---|
| Cost Model | Free (High labor cost) | $40–$150/mo + $6–$12/employee + off-cycle run fees | One-Time License (Zero monthly fees) |
| Calculation Control | High (Error prone) | Rigid black-box rules | 100% customizable in Excel formulas |
| FICA Cap Threshold Logic | Manual recalculation per person | Automated | Automated via piecewise formula |
| Data Privacy & Security | Local disk | Multi-tenant US cloud servers | 100% Offline Local Processing |
| Batch PDF Payslip Generation | Manual Print / Save (Hours) | Portal download | 100+ PDFs in under 30 seconds |
| Password-Protected PDFs | No | Requires portal login | Yes (Automated AES-256) |
| Direct Email Dispatch | Manual individual attachments | Automated system emails | Yes (Custom SMTP server) |
Frequently Asked Questions (FAQs)
Is grossing up an employee bonus legally required by law?
No statutory law mandates that employers must gross up bonuses. However, if an employment agreement, offer letter, or written compensation plan specifies an exact net figure (e.g., "Employee shall receive a net bonus of $5,000"), the employer is contractually bound to cover the associated taxes. Furthermore, grossing up is industry best practice for executive relocations, spot awards, and holiday gifts.
Can an employer use the employee's Form W-4 withholding rate instead of the flat 22% rate?
Under IRS Publication 15-T, if supplemental wages are paid concurrently with regular wages without separate identification, the employer must use regular W-4 wage withholding tables (the Aggregate Method). However, when supplemental wages are paid as a separate off-cycle check or specifically itemized on the paystub, the flat 22% supplemental rate is authorized and strongly preferred for gross-up calculations.
What happens if an employee receives over $1,000,000 in supplemental wages in a year?
IRS regulations require mandatory withholding at the top individual tax rate (37%) on the portion of cumulative supplemental wages exceeding $1,000,000 in a calendar year. In this scenario, your gross-up divisor must incorporate 37% federal withholding rather than 22% for the amount above the threshold.
Does grossing up a bonus guarantee the employee will not owe taxes on Form 1040?
A payroll gross-up covers the statutory withholding requirementsat the time of disbursement. Because individual income tax liabilities depend on an employee's total annual household income, spousal earnings, investment gains, and itemized deductions, the final tax rate at filing may differ from the 22% statutory supplemental withholding rate. Employers are only required to satisfy statutory withholding rules.
How should non-cash fringe benefits (like company trips) appear on the payslip?
Non-cash fringe benefits must appear in the earnings section showing the Fair Market Value (FMV) of the benefit alongside a "Tax Gross-Up Allowance." The total statutory taxes are deducted, and an offsetting non-cash deduction line is applied so that the net cash paycheck disbursement equals $0.00 while the employee's tax obligation is fully settled.
How does PayslipGen handle off-cycle bonus payslips without disrupting regular payroll?
PayslipGen functions entirely offline as an independent payroll engine. You can create a dedicated "Special Bonus Run" spreadsheet at any time, import it into PayslipGen, and generate custom bonus payslips with distinct pay period dates and descriptive line items without incurring off-cycle processing fees or modifying your monthly payroll cycles.
Automate Your Bonus & Gross-Up Payslips Locally
Calculate reverse taxes in your favorite spreadsheet and batch-generate professional, password-protected PDF payslips in seconds with zero recurring monthly SaaS fees.
Get PayslipGen TodayConclusion
Providing employees with bonuses and taxable fringe benefits should be a celebratory milestone that reinforces high performance and organizational culture. By replacing haphazard estimates with the exact algebraic gross-up equation Gross = Net / (1 - Total Tax Rate), finance and HR teams can deliver exact promised take-home earnings with zero payroll shortfalls or compliance risks.
When paired with PayslipGen, your custom Excel calculations are transformed into enterprise-grade, encrypted PDF payslips in seconds. You maintain total data privacy on your local machine, eliminate recurring SaaS subscription overhead, and provide your team with transparent, bank-ready earnings statements every time.
(Looking to streamline other payroll workflows? Read our comprehensive guides on Hourly Overtime Payroll Automation, 1099 Contractor Payment Advice, or how to generate bulk PDF payslips from Google Sheets without script timeouts.)