Clergy Paystub Generator: How to Format Pastor Housing Allowances (IRC §107) from Excel
Key Takeaways
- ✓The Minister Dual-Tax Status: Under federal law, ordained ministers are statutory "hybrid" taxpayers: they are treated as common law employees for Federal Income Tax (FIT) reporting, but as self-employed individuals for Social Security and Medicare (SECA) under IRC § 1402.
- ✓Churches Cannot Withhold FICA: Internal Revenue Code Section 3121(b)(8)(A) strictly exempts religious ministers from standard FICA payroll tax withholding. A church that automatically deducts 7.65% FICA from a pastor's paycheck is in direct violation of federal tax regulations.
- ✓The IRC § 107 Advance Designation Mandate: To qualify for the federal income tax exclusion, a pastor's housing or parsonage allowance must be formally designated in writing by the church governing board prior to payment. Retroactive designations are strictly forbidden.
- ✓Sovereign Church Payroll with PayslipGen: Church treasurers can maintain ministerial salary and housing calculations in a simple, private Excel workbook and use PayslipGen to generate pristine, bank-ready PDF paystubs for a one-time $49 payment—saving hundreds of dollars each year for ministry.
Serving as a church treasurer, deacon, or financial administrator is an honorable labor of love. Yet when it comes to processing pastoral compensation, well-meaning church officers frequently find themselves trapped in a labyrinth of complex IRS regulations.
In the eyes of the Internal Revenue Service, ordained, licensed, or commissioned ministers occupy a unique legal and tax category known as Dual-Tax Status:
- For Federal Income Tax (FIT) purposes, a minister is considered an employee of the church and receives an IRS Form W-2 at year-end.
- For Social Security and Medicare purposes, the minister is classified as self-employed and must pay Self-Employment Contributions Act (SECA) taxes on IRS Schedule SE (Form 1040).
- Under Internal Revenue Code Section 107, the portion of a minister's compensation designated by the church as a "Housing Allowance" is completely exempt from federal income tax, but remains fully subject to SECA tax.
When a church signs up for mainstream commercial payroll software like Gusto, QuickBooks Online Payroll, or ADP, these systems inevitably mangle clergy payroll. Because standard cloud platforms are built for corporate businesses, they reflexively force the standard 7.65% FICA withholding (Social Security and Medicare) on the pastor's salary.
When church treasurers attempt to turn off FICA, the software often errors out or incorrectly reclassifies the pastor as a "1099 Independent Contractor." Issuing a 1099 to an ordained pastor who leads services, manages church staff, and operates under church bylaws violates federal labor law and triggers severe audit penalties.
In this comprehensive clergy payroll guide, we examine the legal mechanics of the Minister Dual-Tax Status, explain the three-tier rule of IRC § 107 Housing Allowances, provide the exact Excel formatting blueprint for church payroll, and show how you can generate compliant, transparent, and password-protected PDF paystubs using PayslipGen for a single one-time payment of $49.
Try Our Interactive Demo Instantly
Want to see how an offline-capable, client-side payslip generator works in practice? Try our brand-new interactive demo right in your browser. Upload a sample CSV, map your columns, and generate beautifully designed PDF payslips—with zero data ever being transmitted to our servers.
Launch Free Demo NowChapter 1: The Minister Dual-Tax Status: FICA Exemption vs. SECA Liability
The most common mistake church treasurers make is treating a pastor like a standard corporate employee. Under Internal Revenue Code Section 3121(b)(8)(A), services performed by a duly ordained, commissioned, or licensed minister of a church in the exercise of ministry are explicitly excluded from the definition of "employment" for FICA tax purposes.
A church is legally prohibited from paying the employer share of FICA (7.65%) or withholding the employee share (7.65%) on wages paid to a qualified minister for ministerial services.
Instead, under IRC § 1402(a)(8), the minister is personally responsible for paying the entire 15.3% Self-Employment (SECA) tax (12.4% Social Security up to the wage base, plus 2.9% Medicare) by filing IRS Schedule SE with their annual Form 1040, making quarterly estimated tax payments via EFTPS.
Voluntary Federal Income Tax Withholding
While mandatory income tax withholding does not apply to ministers under IRC § 3401(a)(9), a pastor and church can mutually agree to voluntary income tax withholding.
The pastor submits an IRS Form W-4 requesting a specific dollar amount to be withheld from each paycheck. A common practice is for the pastor to calculate their expected quarterly SECA tax and request that additional federal income tax be withheld to cover both their income tax and SECA tax liabilities. This shields the pastor from having to submit separate quarterly estimated tax payments.
Chapter 2: The IRC Section 107 Housing Allowance: The Three-Tier Rule
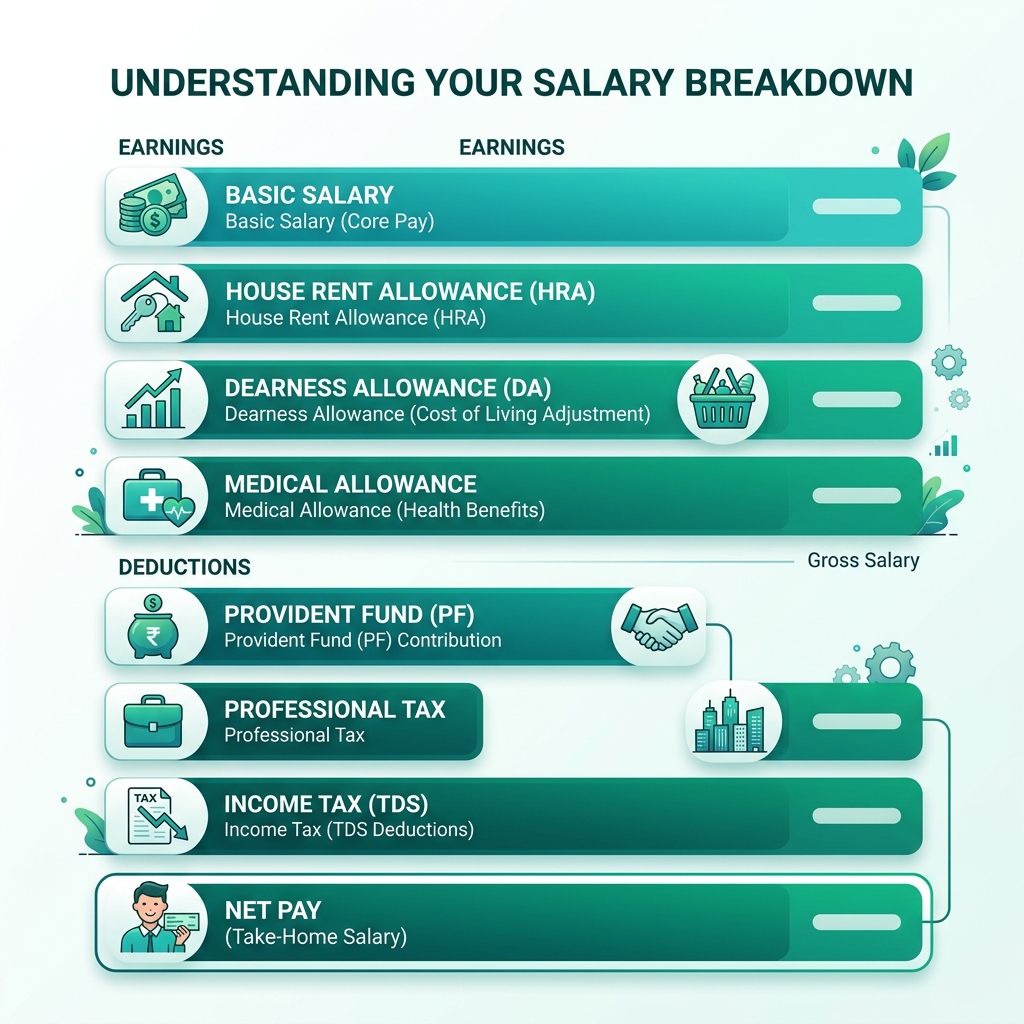
Section 107 of the Internal Revenue Code allows an ordained minister to exclude from gross income a church-designated housing allowance paid as part of compensation, to the extent that it is used to rent or provide a home.
However, the tax code imposes strict operational rules to claim this benefit:
1. The Advance Designation Requirement
The housing allowance must be officially adopted by the church board, congregation, or vestry in writing prior to the calendar year or pay cycle in which the payments are made.
Under Treasury Regulation § 1.107-1, retroactive designations are strictly void. If a church pays a pastor $5,000 in January and designates $2,000 of it as a housing allowance in March, the entire January payment is fully taxable as federal income.
2. The "Lowest of Three" Calculation Rule
Under IRS rules, the amount a minister can actually exclude from federal income tax on Form 1040 is legally limited to the lowest of three amounts:
| Evaluation Metric | How It Is Determined | Example Scenario |
|---|---|---|
| 1. Church Designated Allowance | Official written amount approved in church board minutes | $32,000 / year |
| 2. Actual Qualified Expenses | Mortgage/rent, utilities, property taxes, insurance, repairs, furnishings | $29,500 / year |
| 3. Fair Rental Market Value (FRMV) | What an independent party would pay to rent the furnished home + utilities | $31,000 / year |
| Allowable Federal Tax Exclusion | The LOWEST of the three numbers | $29,500.00 |
In this scenario, because the pastor incurred only $29,500 in actual expenses, the remaining $2,500 of the designated allowance must be added back as taxable income on Form 1040 Line 1h ("Other Earned Income").
Crucially, the entire $32,000 designated amount remains fully subject to SECA tax on Schedule SE.
Chapter 3: Structuring the Master Excel Clergy Payroll Sheet
Because commercial cloud payroll systems fail to manage clergy dual-tax rules, maintaining compensation in an Excel or Google Sheets workbook is the most reliable, audit-proof method for church treasurers:
| Column Header | Sample Value | Formula / Rule | Explanation |
|---|---|---|---|
| Pastor_Name | Rev. David Vance | Text | Minister full legal name |
| Base_Salary | 3500.00 | Currency | Taxable base ministerial pay |
| Housing_Allowance_Desig | 2500.00 | Currency | Approved Section 107 allowance |
| Total_Gross_Disbursement | 6000.00 | =Base_Salary + Housing_Allowance | Total monthly church compensation |
| FICA_Withholding | 0.00 | 0.00 | Exempt by law under IRC § 3121(b)(8) |
| Voluntary_FIT_Withholding | 650.00 | Form W-4 request | Voluntary federal income tax |
| Retirement_403b | 350.00 | Pre-tax deduction | Denominational 403(b)(9) plan |
| Net_Paycheck | 5000.00 | =Total_Gross - Deductions | Net disbursement check / ACH |
Chapter 4: Year-End W-2 Reporting for Ordained Pastors
At the end of the calendar year, the church issues Form W-2 to the minister. Because of the clergy tax rules, completing the W-2 requires exact precision:
- Box 1 (Wages, tips, other compensation): Enter only the pastor's taxable salary (Base Salary minus pre-tax retirement deductions like 403(b)). Do NOT include the housing allowance in Box 1!
- Box 2 (Federal income tax withheld): Enter total voluntary federal income tax withheld throughout the year.
- Boxes 3, 4, 5, and 6 (Social Security & Medicare): LEAVE COMPLETELY BLANK! Do not enter $0.00; leave the boxes empty. Entering figures here triggers automated IRS matching errors.
- Box 14 (Other): Enter the total designated housing allowance labeled clearly:
HOUSING ALLOWANCE $30,000orIRC 107 HOUSING $30,000.
Chapter 5: The 5-Year Cost Burden: Gusto vs. PayslipGen for Churches
Most churches operate on tight tithes and offerings budgets. Surrendering $60 to $80 every month to cloud payroll software just to print one or two paystubs for pastoral staff is poor financial stewardship:
| Horizon | Gusto Core ($40 base + $6/pastor) | QuickBooks Online Payroll ($50/mo) | PayslipGen (One-Time Desktop License) |
|---|---|---|---|
| Year 1 | $552 | $600 | $49.00 (Total) |
| Year 3 | $1,656 | $1,800 | $49.00 (Total) |
| Year 5 | $2,760 | $3,000 | $49.00 (Total) |
| Recurring Monthly Bill | Yes ($46/mo forever) | Yes ($50/mo forever) | ZERO ($0.00 forever) |
Chapter 5B: Year-End W-2 Reporting, Box 14 Documentation, and IRS Audit Shielding
One of the most persistent sources of confusion for church treasurers and volunteer bookkeepers is how monthly paystub data translates to year-end tax forms. Because clergy hold dual tax status, mistakes on Form W-2 are exceptionally common and frequently trigger automated IRS CP2000 matching notices.
Here is the exact protocol for transferring your monthly PayslipGen payroll totals to Form W-2:
- Box 1 (Wages, tips, other compensation):Enter ONLY the minister's taxable ministerial salary plus any taxable fringe benefits. Do NOT include the designated housing allowance here. If the pastor earned $40,000 in base pay and received a $24,000 housing allowance, Box 1 must display exactly $40,000.
- Boxes 3 & 5 (Social Security and Medicare wages): For ordained ministers exempt from FICA under IRC § 3121(b)(8), these boxes must be left completely BLANK. Entering numbers here will cause the Social Security Administration to assess redundant payroll taxes.
- Box 2 (Federal income tax withheld): Report any voluntary federal withholding requested by the pastor on Form W-4.
- Box 14 ("Other"): This is where the church officially informs the IRS and the minister of the housing allowance paid. Use the designation notation
"HOUSING ALLOW $24,000"or"PARSONAGE $24,000".
The Church Board Audit Checklist
To ensure your ministry is fully protected during an IRS or denominational compliance review, keep these four documents in the pastor's confidential personnel file:
- Copy of Ordination / License Certificate: Proof that the worker meets ecclesiastical standards under IRC § 107.
- Signed Housing Resolution Minutes: Board minutes dated and ratified before the first dollar of the tax year was disbursed.
- Minister's Annual Estimate Worksheet: Itemized projection of actual housing expenses submitted by the pastor prior to board approval.
- Monthly Payslip Record: Consistent monthly or bi-weekly paystubs generated via PayslipGen proving transparent breakdown between base salary and housing allowance.
Chapter 6: Generating Clergy Paystubs in 3 Steps with PayslipGen
With PayslipGen, turning your church Excel records into clean, compliant PDF paystubs takes less than two minutes:
- Drop Your Church Spreadsheet: Drag your monthly Excel workbook into PayslipGen on your local church computer.
- Map Ministry Headers: Select Base Salary, Housing Allowance, Voluntary FIT, and 403(b) Retirement deductions. The layout engine permanently remembers your church configuration.
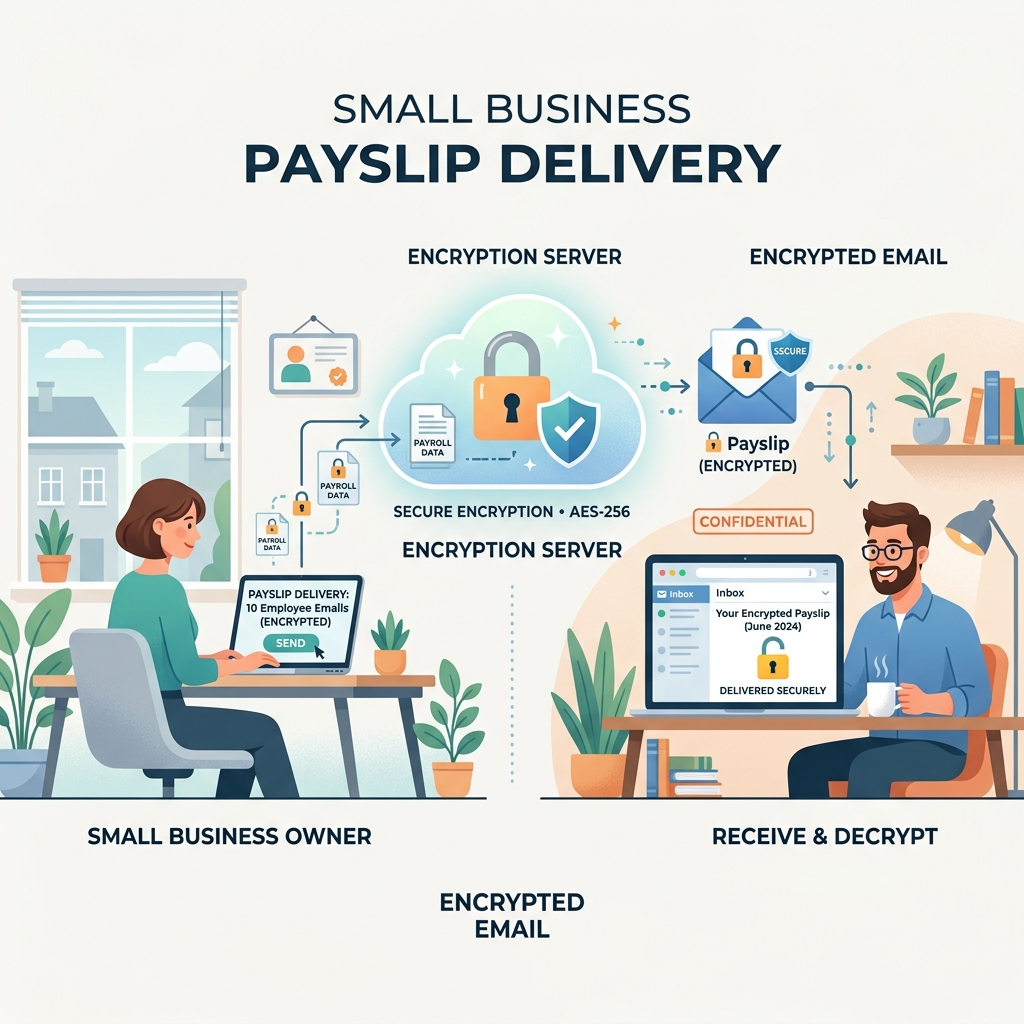
- Password Protect & Deliver:Lock the output PDF with the pastor's Date of Birth and export to PDF or email directly to their inbox with a personalized note.
Frequently Asked Questions (FAQs)
Can a church designate 100% of a pastor's compensation as housing allowance?
Yes, if officially designated by the church board in advance. However, the minister can only legally exclude the portion that corresponds to actual qualified expenses or fair rental value. Any excess designated amount must be reported as taxable income on Form 1040 Line 1h.
Why do mortgage underwriters struggle with clergy paystubs?
Mortgage lenders who are unfamiliar with church payroll often look at W-2 Box 1 and assume the pastor earns very little, failing to realize that the housing allowance in Box 14 is real cash income. Providing institutional, itemized paystubs from PayslipGen showing Total Gross Earnings ($6,000/mo) alongside itemized housing allowances gives underwriters immediate clarity on qualifying income.
Can non-ordained church staff (administrators, worship leaders) receive a housing allowance?
No. Under IRC § 107, the housing allowance exclusion applies strictly to duly ordained, commissioned, or licensed ministers performing ministerial duties (sacerdotal functions, conducting religious worship, managing religious organizations). Non-ordained staff are standard W-2 employees subject to mandatory FICA withholding.
Does PayslipGen store church financial records on the internet?
No. PayslipGen is 100% offline desktop software. Your pastor's compensation, Social Security Number, and church banking records reside exclusively on your local computer hard drive.
Can I also generate paystubs for non-ordained church employees in the same batch?
Yes. Your spreadsheet can contain both ordained ministers (exempt from FICA) and non-ordained custodians or administrative assistants (with standard FICA withholdings). PayslipGen processes all employee types in one click.
Simplify Clergy Payroll for Just $49
Generate compliant, itemized clergy paystubs with Section 107 housing allowances directly from your spreadsheet. No monthly subscriptions, lifetime access, and complete local privacy.
Get PayslipGen for $49 (Lifetime Access)Conclusion: Faithful Church Stewardship Starts with Clear Records
Pastoral ministry is demanding work. Providing ministers with professional, legally accurate compensation statements demonstrates honor and protects both the pastor and the congregation from tax complications.
You do not need to surrender hundreds of dollars of church funds to cloud software providers every year. By maintaining a clean Excel record and pairing it with PayslipGen, your church achieves total IRS compliance, complete financial privacy, and institutional-grade paystubs with a single, one-time investment of $49.
(Managing other non-profit or small business payrolls? Explore our guides on Low-Cost Payslip Generation for Nonprofits, S-Corp Owner Salary Paystubs, or how to Generate Password-Protected Payslips.)