Travel Physical Therapist Paystub Generator: How Allied Health Staffing Splits Tax Home Per Diems, Blended Rates & GSA Stipends in Excel
Key Takeaways
- ✓The Three-Part Tax Home Rule (IRC § 162(a)): For travel physical therapists (PT), occupational therapists (OT), and speech-language pathologists (SLP) to receive tax-free travel stipends, they must maintain a legitimate permanent tax home incurring duplicated living expenses. Without proof of duplicate housing, all per diem stipends become 100% taxable back wages.
- ✓The 50-Mile Myth vs. Rest Rule: The popular "50-mile rule" has zero statutory basis in IRS code. The true legal benchmark under Revenue Ruling 75-170 is whether the clinical assignment requires an overnight rest or sleep period away from the permanent tax home.
- ✓Wage Recharacterization Trap (Clarke v. AMN Services): Staffing agencies that artificially reduce taxable hourly wages to $20/hr while boosting non-taxable stipends to inflate take-home pay face severe class-action and IRS liabilities. Overtime must be calculated on the true regular rate of pay including wage-equivalent stipends.
- ✓Air-Gapped Privacy for Allied Health Staffing: Boutique healthcare staffing firms managing traveling clinicians cannot afford $1,200/month Bullhorn or BlueSky subscriptions. Using PayslipGen, agencies generate compliant, password-encrypted PDF travel compensation vouchers directly from Excel for a one-time $49 payment.
Across outpatient orthopedic clinics, skilled nursing facilities (SNFs), home health agencies, and acute care hospitals, the demand for traveling physical therapists (PTs), occupational therapists (OTs), and speech-language pathologists (SLPs) is at an all-time high. Clinical staffing agencies place therapists on 13-week contracts across state lines, offering lucrative weekly pay packages.
However, beneath these headline weekly guarantees ($1,800 to $2,800/week) lies the most scrutinized compensation architecture in United States labor and tax law: the dual-rate "blended compensation package." A travel therapist's weekly payout is split between taxable hourly wages (subject to federal, state, and FICA withholdings) and non-taxable expense reimbursements under the U.S. General Services Administration (GSA) per diem benchmarks for lodging, meals, and incidentals (M&IE).
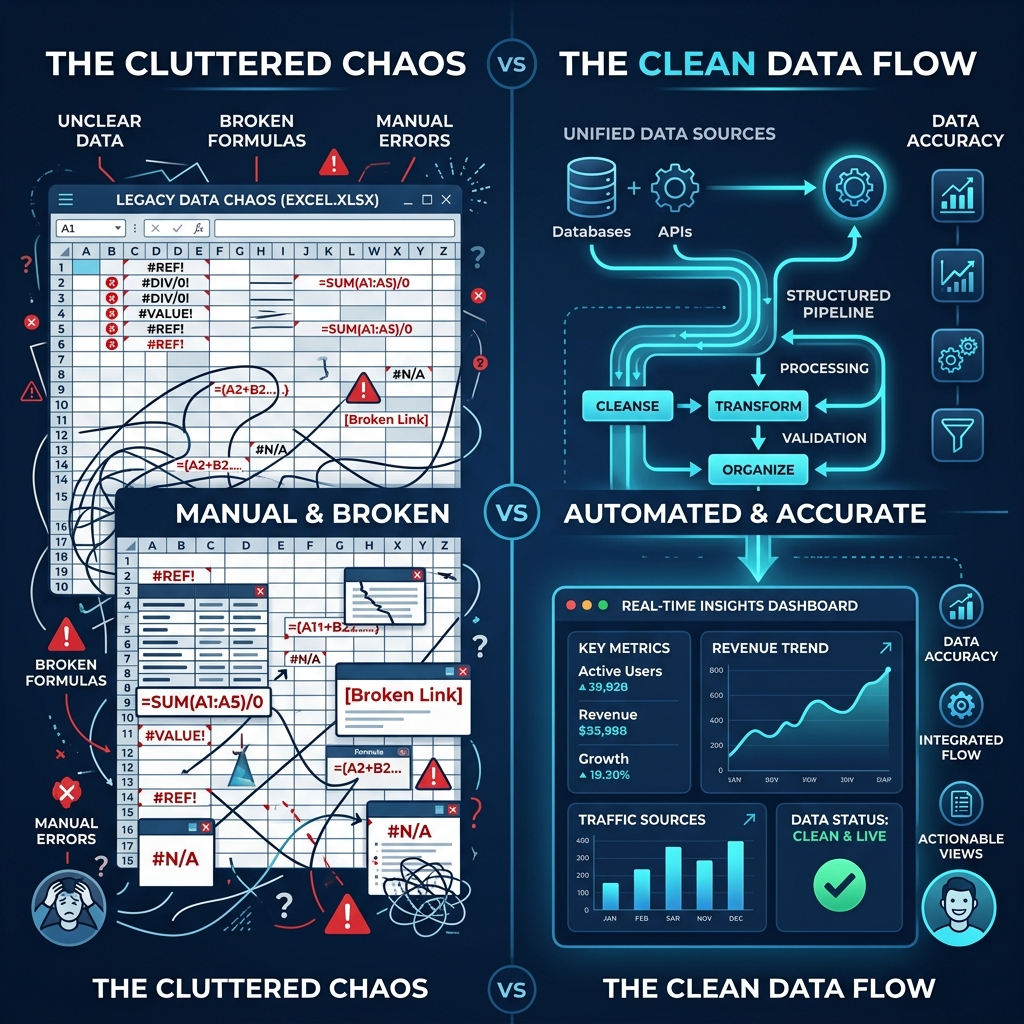
When boutique therapy staffing agencies or clinical recruiting firms process these complex split disbursements using rigid cloud payroll platforms like Gusto, ADP, or QuickBooks, they encounter endless friction. These platforms cannot natively format GSA tax-exempt stipends, fail to handle variable meal penalty deductions, and charge recurring monthly SaaS fees ($500 to $2,500/month) that squeeze agency margins.
Try Our Interactive Demo Instantly
Want to see how an offline-capable, client-side payslip generator works in practice? Try our brand-new interactive demo right in your browser. Upload a sample CSV, map your columns, and generate beautifully designed PDF payslips—with zero data ever being transmitted to our servers.
Launch Free Demo NowChapter 1: The Legal Anatomy of an Allied Health Travel Package
Under Internal Revenue Code (IRC) § 62(a)(2)(A) and Treasury Regulations § 1.62-2, an employer may reimburse traveling clinicians for travel expenses on a tax-free basis only if paid under an Accountable Plan. An Accountable Plan mandates three immutable conditions:
- Business Connection: The therapist incurs expenses while performing clinical services as an employee away from their tax home.
- Substantiation: Expenses must be substantiated through proof of duplicate lodging and travel records, or deemed substantiated via federal GSA per diem rates.
- Return of Excess Amounts: Any reimbursement exceeding actual substantiated days worked must be returned to the staffing agency.
The Three-Factor Tax Home Test (Rev. Rul. 73-529)
For a clinician to receive tax-free stipends, they must possess a legitimate permanent "tax home." The IRS uses three criteria under Revenue Ruling 73-529:
- Factor 1: Principal Business: The therapist performs part of their business in the vicinity of the claimed home and lives there while working.
- Factor 2: Duplicated Living Expenses: The therapist incurs real, ongoing living expenses (mortgage, fair-market rent, utilities) at their permanent home that are duplicated when renting short-term housing at the 13-week assignment location.
- Factor 3: Personal Ties: The therapist maintains family, historical lodging, and administrative ties (driver's license, voting, bank accounts) at the permanent residence.
| Paystub Line Item | Typical Weekly Amount | Tax & Withholding Status |
|---|---|---|
| Taxable Hourly Clinical Wages (36 hrs @ $24/hr) | $864.00 | Fully taxable (Federal, State, FICA, Medicare) |
| Non-Taxable GSA Lodging Stipend (7 days) | $980.00 ($140/day) | Tax-exempt under Accountable Plan |
| Non-Taxable Meals & Incidentals (M&IE) | $448.00 ($64/day) | Tax-exempt under Accountable Plan |
| Travel Relocation Reimbursement | $250.00 (One-time) | Taxable unless substantiated under accountable mileage |
| Total Weekly Gross Disbursement | $2,542.00 | $1,428.00 Tax-Free / $1,114.00 Taxable |
Chapter 2: The Clarke v. AMN Services Ruling & FLSA Overtime
The most perilous legal pitfall in allied health travel staffing stems from the landmark Ninth Circuit Court of Appeals decision in Clarke v. AMN Services, LLC (987 F.3d 848).
In Clarke, the court ruled that when an agency prorates per diem stipends based on the number of clinical hours worked (e.g., deducting $35 of lodging stipend for every missed hour of a shift), those per diems are legally functioning as wage substitutes rather than true expense reimbursements.
The Consequence: When stipends function as wage substitutes, they MUST be incorporated into the clinician's Regular Rate of Pay for calculating overtime under the Fair Labor Standards Act. If a therapist works 48 hours on a 36-hour contract, paying overtime calculated solely on their $24/hr base rate instead of their blended $55/hr effective rate constitutes willful wage theft under federal law!
Chapter 3: Excel Blueprint: Allied Health Travel Staffing Payroll
Staffing coordinators can manage multiple traveling therapists across different hospital systems and GSA zones with this structured Excel workbook:
| Col | Header Name | Formula / Type | Description |
|---|---|---|---|
| A | Clinician_ID | Text (e.g., PT-882) | Therapist identifier |
| B | Therapist_Name | Text | Full clinician name |
| C | Clinical_Hours | Numeric (e.g., 40.0) | Approved clinic or hospital hours |
| D | Hourly_Base_Wage | Currency (e.g., 25.00) | Taxable base hourly rate |
| E | Taxable_Wages | =C2*D2 | Gross taxable earnings |
| F | GSA_Lodging_Stipend | Currency (e.g., 1050.00) | Non-taxable weekly lodging allowance |
| G | GSA_MIE_Stipend | Currency (e.g., 462.00) | Non-taxable weekly meals & incidentals |
| H | Total_NonTaxable | =F2+G2 | Total tax-free per diem |
| I | Total_Disbursement | =E2+H2-Taxes | Net payout to therapist bank account |
Chapter 4: Why Cloud SaaS Fails Allied Health Staffing Firms
Allied health agencies face brutal market dynamics: vendor management systems (VMS portals like Fieldglass and Medefis) take 3%–5% MSP fees, while hospital bill rates face margin compression. When an agency places 15 traveling PTs and OTs, cloud staffing software vendors (Bullhorn, BlueSky, or Workday) demand between $8,000 and $25,000 in annual licensing contracts!
Moreover, cloud portals expose highly sensitive clinician credentialing data—Social Security Numbers, state PT/OT licenses, physical exam records, and personal bank routing details—to third-party cloud data leaks.
With PayslipGen, agencies retain 100% data sovereignty. The software runs locally on your workstation, handles non-taxable vs. taxable wage formatting effortlessly, and costs a one-time flat fee of $49 for life.
Chapter 5: Generate Travel PT Paystubs with PayslipGen
- Export Weekly VMS Timesheets to Excel: Collate facility-approved hours, GSA per diem allocations, and taxable rates into your Excel template.
- Import File into PayslipGen: Launch the offline application. Load your
.xlsxor.csvworkbook. - Map Allied Health Line Items:
Taxable_Wages→ Base Salary / Hourly EarningsGSA_Lodging_Stipend→ Non-Taxable Allowance 1GSA_MIE_Stipend→ Non-Taxable Allowance 2Total_Disbursement→ Net Pay
- Encrypt with Clinician DOB or SSN-4: Set individual password protection so traveling therapists can securely open their pay vouchers on their mobile phones.
- Batch Generate & Email:Click "Generate Payslips". PayslipGen delivers crisp, branded, audit-proof PDF vouchers to all clinicians in seconds via private SMTP.
Frequently Asked Questions (FAQs)
What is the 12-month rule for travel physical therapists?
Under IRC § 162(a), a travel assignment in a single metropolitan area is considered temporary only if it lasts for one year or less. If a travel PT extends their contract at the same hospital or takes consecutive assignments in the same metro area exceeding 12 continuous months, their tax home shifts to the assignment location. From that moment, all subsequent stipends become fully taxable wages.
Can a travel therapist return home on weekends and still receive full 7-day per diems?
Yes, provided the therapist continues to maintain and pay for their duplicate lodging at the assignment location over the weekend. Because short-term rentals and monthly leases charge 7 days a week, the duplicate living expense test is satisfied. However, if the clinician checks out of a daily hotel on Friday and returns home, weekend stipends cannot be paid tax-free.
Why is the "50-mile rule" considered a healthcare staffing myth?
The IRS code contains no 50-mile rule for travel healthcare stipends. The 50-mile threshold is an internal hospital policy used to prevent local therapists from taking lucrative travel contracts. For tax purposes, the sole criterion is whether the distance reasonably requires an overnight stay to obtain necessary rest between shifts.
How must stipends appear on the clinician's annual Form W-2?
Stipends paid under a valid Accountable Plan are completely excluded from Form W-2 Box 1 (Taxable Wages), Box 3 (Social Security Wages), and Box 5 (Medicare Wages). They are recorded in Box 12 under Code L (Substantiated employee business expense reimbursements) for informational reporting only.
Does PayslipGen support multi-state taxation for traveling therapists?
Yes. Because you control your spreadsheet formulas, you can calculate specific state withholding (e.g. resident state vs. assignment work state reciprocity) and map those distinct tax deductions directly onto the generated paystub voucher.
Scale Allied Health Staffing Payroll for Just $49 Once
Stop paying predatory monthly cloud fees to Bullhorn or BlueSky. Generate compliant, encrypted, and audit-ready travel PT, OT, and SLP paystubs directly from your Excel sheets.
Get PayslipGen for $49 (Lifetime Access)Conclusion: Compliant Stipend Payroll Protects Agency Valuation
In healthcare staffing, agency valuation and credentialing audits hinge on clean compliance. Conflating non-taxable stipends with taxable clinical hours invites devastating IRS audits and FLSA collective actions under Clarke v. AMN Services.
By leveraging an organized Excel workflow paired with PayslipGen, allied health staffing firms maintain complete compliance, safeguard clinician PII offline, and disburse professional paystubs without paying monthly cloud tolls.
(Interested in other clinical travel and medical payroll workflows? Explore our detailed guides on Travel Nurse GSA Stipends, Locum Tenens Physician Settlements, and Dental Hygienist Production Rates.)