Locum Tenens Physician Paystub Generator: 1099 vs W-2 Per Diem, Malpractice Tail & Travel Stipends in Excel
Key Takeaways
- ✓Dual Classification Realities (1099 vs. W-2): Locum tenens physicians are staffed either as common-law employees (W-2) or independent contractors (1099-NEC) depending on hospital credentialing rules and the IRS Revenue Ruling 87-41 20-factor behavioral control test. Paystubs must cleanly isolate statutory withholding from self-employed gross disbursements.
- ✓IRS Accountable Plan Per Diem Rules: Lodging stipends and Meals & Incidentals (M&IE) qualify for non-taxable treatment under IRC § 62(a)(2)(A) only if the physician maintains a substantiated, duplicate-expense tax home. Prorating per diems based on clinical hours worked invites dangerous wage recharacterization penalties under Clarke v. AMN Services.
- ✓Malpractice Tail Insurance Escrow Holdbacks: When claims-made professional liability policies are utilized, staffing agreements frequently mandate escrow holdbacks (e.g., $1,000–$2,500 per assignment block) to fund extended reporting endorsement "tail" coverage if the doctor departs prematurely.
- ✓Air-Gapped Desktop Batching: Clinical staffing agencies managing dozens of traveling doctors cannot afford cloud SaaS subscription drains ($600–$2,400/month on Bullhorn or BlueSky) or cloud data leakage of physician NPI, DEA, and SSN records. Using PayslipGen, agencies generate password-protected, audit-ready PDF physician vouchers directly from Excel for a one-time $49 payment.
In hospital executive suites and physician staffing agencies across the United States, managing locum tenens compensation is one of the most legally intricate operations in healthcare administration. When a board-certified emergency physician, trauma surgeon, or hospitalist steps in to cover rural hospital shortages or specialty leaves, their weekly disbursement is rarely a standard paycheck.
Instead, a locum physician's settlement represents a high-stakes convergence of contractual day rates, intensive night shift differentials, non-taxable GSA lodging stipends, meals and incidentals (M&IE), and malpractice tail insurance escrow deductions. A single calculation error or reporting misstep on a doctor's settlement statement can trigger severe IRS payroll audits, state Department of Revenue reclassification penalties, or bitter clinical contract disputes that leave critical hospital units unstaffed.
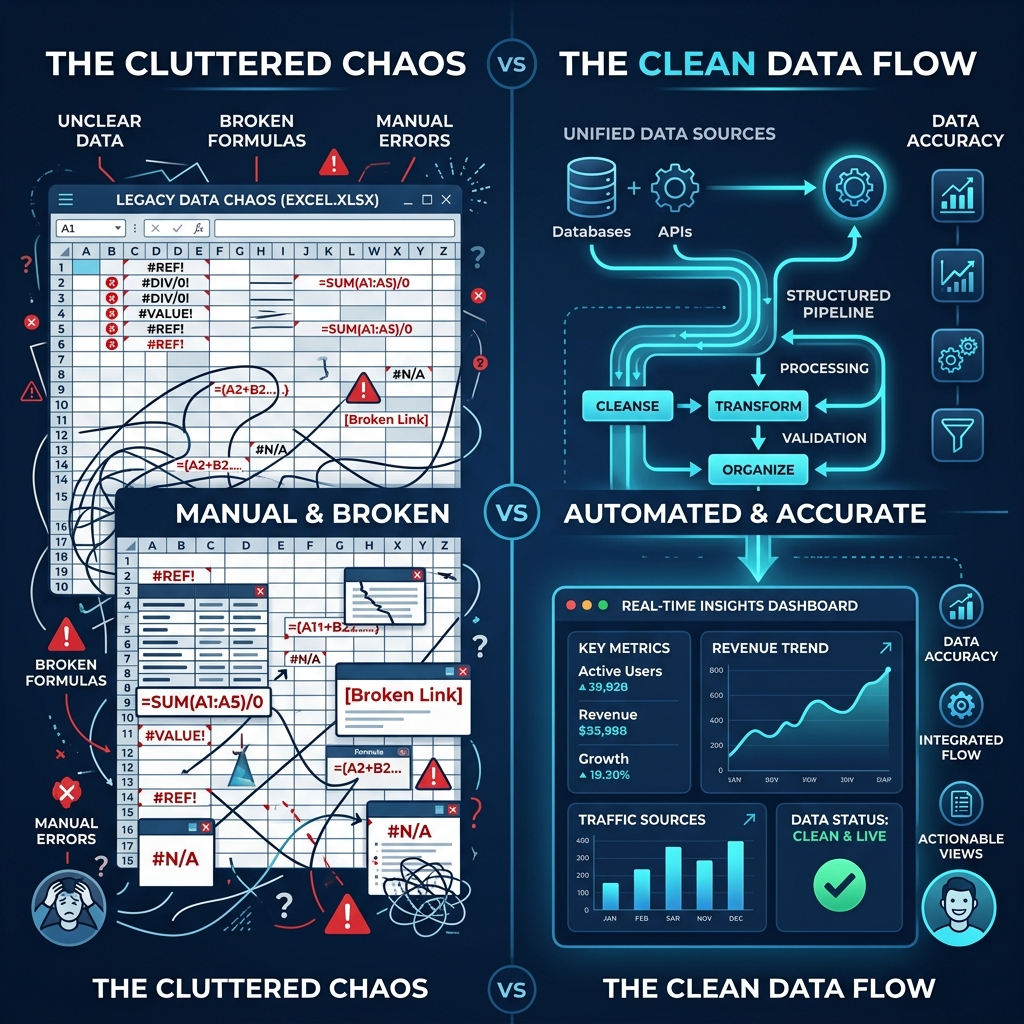
Yet many medical staffing firms, physician practice groups, and hospital credentialing coordinators still struggle with broken formulas in legacy spreadsheets or find themselves trapped paying thousands in perpetual monthly fees to bloated cloud staffing platforms like Bullhorn, BlueSky, or Workday.
Try Our Interactive Demo Instantly
Want to see how an offline-capable, client-side payslip generator works in practice? Try our brand-new interactive demo right in your browser. Upload a sample CSV, map your columns, and generate beautifully designed PDF payslips—with zero data ever being transmitted to our servers.
Launch Free Demo NowChapter 1: The Clinical Staffing Reality: 1099 vs. W-2 Classification
The foundational challenge of locum tenens payroll is determining the doctor's statutory worker classification. Unlike permanent clinical staff who are virtually always classified as standard W-2 employees, traveling physicians operate across a spectrum of legal structures.
The IRS 20-Factor Common Law Control Test (Rev. Rul. 87-41)
Under Internal Revenue Service Revenue Ruling 87-41, the IRS established twenty common-law factors to evaluate whether an employment relationship exists. In clinical environments, these factors center on three broad categories:
- Behavioral Control: Does the healthcare facility direct and control how the physician performs clinical tasks? While hospitals dictate medical staff bylaws, credentialing standards, and EHR usage (Epic, Cerner), the physician exercises independent professional medical judgment regarding diagnosis, patient care protocols, and treatment regimens.
- Financial Control: Does the doctor have a significant investment in facilities or equipment? Does the doctor realize a profit or loss? Locum physicians often carry their own business entity (Professional Corporation, LLC, or S-Corporation), pay their own state medical licensing board renewal fees, and negotiate fixed daily guarantees.
- Relationship of the Parties: Are there written independent contractor contracts specifying temporary assignment duration, lack of employee fringe benefits (401k match, paid annual vacation, health insurance), and clear discharge parameters?
| Classification Dimension | 1099 Independent Contractor Doctor | W-2 Employed Locum Physician |
|---|---|---|
| Tax Reporting Form | Form 1099-NEC (Box 1) | Form W-2 (Boxes 1, 2, 3, 5) |
| Payroll Tax Withholding | None; Doctor pays 15.3% SECA on Schedule SE | Mandatory FICA (6.2% SS + 1.45% Med + 0.9% Additional) + FITW |
| Travel Stipend Handling | Gross paid without tax, or bundled into gross contractor rate | Must meet IRC § 62 Accountable Plan rules to remain non-taxable |
| Hospital Facility Preference | Common in private practices, commercial locums agencies | Required by VA hospitals, academic health centers, state clinics |
| Overtime Eligibility | Exempt; contractual hourly or daily rate applies | Exempt under FLSA 29 CFR § 541.304 (Learned Professionals) |
Audit Alert: Multi-State Agency Exposure
Several states (including California under AB 5 / Labor Code § 2750.3 and Massachusetts under M.G.L. c. 149, § 148B) enforce strict statutory tests. While physicians are granted specific exemptions under California's ABC test, healthcare agencies must still establish that the physician maintains an independent practice, contracts freely with multiple hospital systems, and holds independent professional liability insurance.
Chapter 2: GSA Per Diem Stipends, Tax Homes & The Accountable Plan Mandate
Traveling physicians incur massive travel expenses: commercial flights, rental vehicles, high-end short-term lodging, and daily meal expenses. Under the Internal Revenue Code, paying these expenses tax-free requires rigorous adherence to statutory Accountable Plan guidelines.
The Three Pillars of an Accountable Plan (IRC § 62(a)(2)(A))
Under Treasury Regulation § 1.62-2, an allowance or reimbursement arrangement qualifies as a non-taxable Accountable Plan only if it meets three statutory tests:
- Business Connection:The expense must have a direct business connection to the clinical assignment. Travel must occur away from the physician's established tax home overnight.
- Substantiation: The doctor must substantiate the time, place, and business purpose of the travel within a reasonable period. Agencies utilizing federal General Services Administration (GSA) per diem rates meet this requirement without collecting individual restaurant or hotel receipts, provided days worked match lodging dates.
- Return of Excess Payments: Any advance or reimbursement exceeding federal GSA maximums or unworked assignment days must be returned to the agency within 120 days.
The "Tax Home" Prerequisite (Revenue Ruling 73-529)
A physician cannot legally receive tax-free per diem stipends if they are classified as an itinerant worker. To qualify for non-taxable housing and meal stipends, the physician must prove a legitimate "Tax Home" under Rev. Rul. 73-529 by demonstrating at least two of the following:
- The physician performs significant clinical or consulting work in the vicinity of their primary residence.
- The physician incurs continuous, duplicate living expenses (mortgage, real estate taxes, utilities, upkeep) at their permanent physical home while away on assignment.
- The physician has historical personal, family, and civic ties to the home locality.
Legal Precedent: The Clarke v. AMN Services Doctrine
In Clarke v. AMN Services, LLC (987 F.3d 848, 9th Cir. 2021), federal appellate courts ruled that when healthcare staffing agencies prorate or reduce per diem stipends based on the number of clinical hours worked in a shift, those stipends function as disguised hourly wages. Consequently, the non-taxable exemption is destroyed, exposing the agency to massive back-tax assessments, penalties, and unpaid regular rate overtime claims.
Chapter 3: Clinical Compensation Mechanics: Guarantees, Differentials & Malpractice Tail
Physician staffing contracts feature specialized compensation mechanisms designed to ensure round-the-clock hospital coverage while insulating facilities against clinical liability risks.
1. Daily & Hourly Clinical Guarantees
Locum physicians rarely accept unbuffered hourly wages. Contracts establish guaranteed daily shift compensation (e.g., $2,600 for a 12-hour emergency room shift or $2,200 for an 8-hour hospitalist rounding shift). If patient census is low and the physician is released after 4 hours, the full daily guarantee remains payable.
2. Hospital Shift Differentials & Surge Premiums
Clinical shifts vary dramatically in intensity. Standard locum fee schedules incorporate tiered differentials:
- Nocturnist Differential: Night coverage (19:00 to 07:00) incurs an automatic premium of $250 to $500 per shift above daytime rounding rates.
- Unassigned Emergency Call Guarantee: Surgeons and OB/GYNs on backup call receive a flat availability rate (e.g., $750/24-hour block) plus an elevated hourly rate (e.g., $325/hr) with a 2-hour minimum if called into the operating room.
- Holiday Surge Premiums: Shifts worked on major federal holidays are compensated at 1.5× to 2.0× standard shift rates.
3. Medical Malpractice Insurance & Tail Coverage Escrow Holdbacks
Professional liability insurance is the lifeblood of clinical staffing. Medical malpractice policies generally fall into two categories:
- Occurrence Policies: Cover any clinical incident that occurred while the policy was active, regardless of when the lawsuit is filed years later. These policies carry massive upfront premiums.
- Claims-Made Policies: The predominant model in locum tenens. Coverage applies only if the policy is actively in force both when the clinical incident occurred and when the formal lawsuit is filed.
When a locum assignment ends, a Tail Policy (Extended Reporting Endorsement) must be purchased to protect against future lawsuits. Tail coverage costs between 150% and 250% of the annual mature premium (often $10,000 to $40,000 depending on specialty, such as neurosurgery or obstetrics).
To protect the staffing agency against breach of contract if a doctor terminates an assignment early, contracts frequently incorporate Malpractice Tail Escrow Holdbacks (e.g., $1,500 withheld per assignment pay period, up to a $6,000 escrow ceiling). If the physician fulfills the complete contract, the escrow is refunded; if they abandon the assignment, the funds are forfeited to offset tail insurance premiums.
Chapter 4: Master Excel Locum Tenens Payroll Blueprint (With Formulas)
To maintain audit compliance across dozens of clinical providers, staffing coordinators and medical practice administrators must structure their payroll spreadsheets with rigorous separation of taxable and non-taxable components.
Below is the exact production architecture for a multi-specialty locum tenens roster, showing the row logic, source data, and Excel formulas:
| Line # | Component Category | Clinical Item Description | Assignment Values | Excel Formula Specification |
|---|---|---|---|---|
| 01 | Clinical Guarantee | Emergency Medicine Day Shifts | 7 shifts @ $2,400.00/shift | =B10*C10 ($16,800.00) |
| 02 | Shift Differential | Nocturnist Graveyard Premium | 4 shifts @ $450.00/shift | =B11*C11 ($1,800.00) |
| 03 | On-Call Callout | Trauma Surge Surgical Hours | 6.5 hours @ $285.00/hr | =B12*C12 ($1,852.50) |
| 04 | TOTAL TAXABLE CLINICAL | Gross Professional Fees | $20,452.50 | =SUM(E1:E3) |
| 05 | Non-Taxable Per Diem | GSA Lodging Allowance | 14 nights @ $178.00/night | =B14*C14 ($2,492.00) |
| 06 | Non-Taxable Per Diem | GSA M&IE Daily Allowance | 14 days @ $74.00/day | =B15*C15 ($1,036.00) |
| 07 | Direct Reimbursement | Rental Car & Airport Parking | Accountable Expense Receipts | $685.40 |
| 08 | Contract Escrow | Malpractice Tail Holdback | Escrow Agreement Block 2 of 4 | -$1,500.00 |
| 09 | 1099 NET REMITTANCE | Total Disbursed to Doctor LLC | $23,165.90 | =E4+E5+E6+E7+E8 |
Multi-Provider Clinical Settlement Roster
When running bi-weekly or monthly disbursements across diverse medical disciplines, the agency master sheet reconciles different classification types and escrow deductions side by side:
| Physician Provider | Specialty / Setting | Class | Taxable Fees | GSA Stipends | Tail Escrow | Tax Withholding | Net Disbursement |
|---|---|---|---|---|---|---|---|
| Dr. Sophia Patel, MD | Emergency Medicine (Level 1) | 1099 | $20,452.50 | $4,213.40 | -$1,500.00 | $0.00 | $23,165.90 |
| Dr. Marcus Vance, DO | Hospitalist / Nocturnist | W-2 | $17,600.00 | $3,420.00 | $0.00 | -$5,456.00 | $15,564.00 |
| Dr. Elena Rostova, MD | General Surgery (Rural Access) | 1099 | $26,800.00 | $3,850.00 | -$2,500.00 | $0.00 | $28,150.00 |
| Dr. Julian Hayes, MD | Pediatric Intensive Care (PICU) | W-2 | $19,200.00 | $3,680.00 | $0.00 | -$5,952.00 | $16,928.00 |
| TOTALS | $84,052.50 | $15,163.40 | -$4,000.00 | -$11,408.00 | $83,807.90 | ||
Chapter 5: Why Healthcare Staffing Agencies Need Air-Gapped Desktop Software
Healthcare staffing coordinators routinely discover that standard enterprise payroll and HR platforms are actively hostile to the realities of locum tenens operations:
1. Severe Security & Data Sovereignty Demands
Physician payroll records contain sensitive commercial and personal identifiers: National Provider Identifiers (NPI), state medical license numbers, DEA registrations, Federal Employer Identification Numbers (FEIN), home addresses, and negotiated daily billing rates. Uploading these records to third-party multi-tenant cloud platforms creates compliance liabilities and exposes proprietary agency margins to data breaches.
With PayslipGen, the entire calculation and PDF generation pipeline runs 100% locally on your computer. Zero patient or provider data ever touches an external server.
2. Elimination of Cloud Staffing SaaS Taxes
Specialized healthcare staffing software (such as Bullhorn, BlueSky, or TargetRecruit) bills astronomical monthly software fees: between $150 and $350 per recruiter seat per month, plus transaction fees on every processed timesheet. A boutique staffing firm with 5 coordinators pays $15,000 to $25,000 every single year merely to generate settlement vouchers!
3. Individualized AES-256 PDF Encryption
When delivering settlement statements to traveling doctors across multiple hospital sites, emailing unencrypted PDFs violates modern data protection protocols. PayslipGen allows staffing coordinators to automatically lock every exported PDF with unique physician passwords (such as the doctor's Date of Birth or the last 4 digits of their SSN/TIN) in a single batch click.
Chapter 6: 5-Year Financial Analysis: $49 Lifetime vs. SaaS Subscriptions
Let's analyze the operational cost of running locum tenens payroll for a medical staffing agency or independent hospital practice group with 15 active traveling physicians over a 5-year period:
| Cost Dimension | Bullhorn / BlueSky Staffing SaaS | Gusto / ADP Cloud Payroll | PayslipGen (One-Time Desktop License) |
|---|---|---|---|
| Monthly Platform Base Fee | $250.00 / mo ($3,000/yr) | $80.00 / mo ($960/yr) | $0.00 (Forever) |
| Per-Physician Monthly Seat Fee | $18.00 / doc / mo ($3,240/yr) | $12.00 / doc / mo ($2,160/yr) | $0.00 (Unlimited doctors) |
| 1099 + W-2 Dual Module Fee | Included only in Enterprise tiers | Additional $2.00/contractor/month | Fully Supported Locally |
| Data Sovereignty & Offline Mode | Cloud Only (Multi-tenant) | Cloud Only | 100% Offline / Local Desktop |
| Year 1 Net Cost | $6,240.00 | $3,480.00 | $49.00 total |
| Year 3 Cumulative Cost | $18,720.00 | $10,440.00 | $49.00 total |
| Year 5 Cumulative Cost | $31,200.00 | $17,400.00 | $49.00 (Lifetime) |
Over a 5-year operating window, choosing PayslipGen saves healthcare agencies between $17,000 and $31,000 in software overhead—capital directly re-deployable toward physician recruiting bonuses and credentialing verification.
Chapter 7: Step-by-Step Workflow: Generating Locum Paystubs in PayslipGen
Transforming raw Excel provider schedules into pristine, encrypted PDF settlement sheets takes less than two minutes:
Step 1: Finalize Your Master Timesheet Workbook
In Microsoft Excel or Google Sheets, organize your bi-weekly disbursement columns: Physician Name, Specialty, Tax Classification (1099 or W-2), Clinical Guarantee Fees, Shift Differentials, Non-Taxable GSA Per Diem, Malpractice Escrow Deduction, and Net Pay.
Step 2: Launch PayslipGen & Define the Medical Staffing Profile
Open PayslipGen on your desktop. Enter your staffing agency or medical practice details: Corporate Legal Name, Practice Address, Federal Tax EIN, and Clinical Payroll Support Contact.
Step 3: Drag and Drop the Excel File
Drag your .xlsx or .csv roster directly into the PayslipGen dashboard. The local parser instantly loads all columns without uploading sensitive physician data to the web.
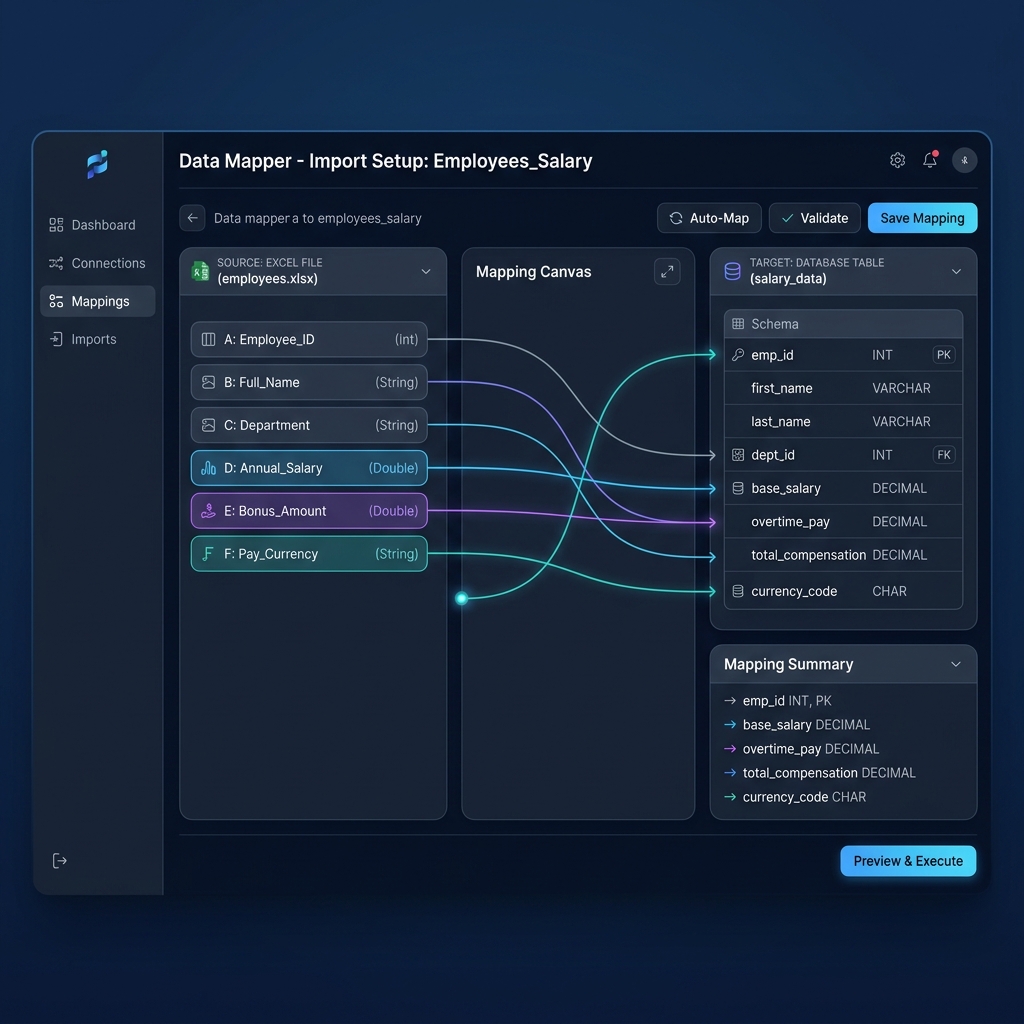
Step 4: Map Custom Healthcare Payroll Columns
Link your spreadsheet headers to PayslipGen's clean template fields:
Taxable_Clinical_Fees→ Gross Earnings / Base GuaranteeShift_Differentials→ Premium Pay / Night DifferentialGSA_Lodging_Allowance→ Non-Taxable Allowance 1GSA_MIE_Allowance→ Non-Taxable Allowance 2Malpractice_Tail_Escrow→ Other Pre-Tax DeductionNet_Disbursement→ Net Pay
Step 5: Apply Password Protection & Batch Generate
Enable automated PDF password encryption using the physician's Date of Birth (YYYYMMDD) or the last four digits of their Taxpayer Identification Number. Select your preferred template, customize brand colors, and click "Generate Payslips". Within seconds, PayslipGen compiles publication-ready, mathematically verified PDF vouchers into an organized local directory.
Frequently Asked Questions (FAQs)
Can a 1099 locum tenens doctor receive non-taxable GSA per diem stipends?
Yes, but the tax mechanics differ between 1099 independent contractors and W-2 employees. When an agency pays per diems to a 1099 physician under an Accountable Plan, those reimbursements are excluded from Form 1099-NEC Box 1. However, many agencies choose to pay an all-inclusive daily guarantee on Form 1099-NEC, allowing the physician to deduct substantiated travel expenses, lodging, and 50% of meals directly on their Schedule C (Form 1040) against their self-employment earnings.
How does the 12-month rule affect locum tenens tax homes?
Under IRC § 162(a), an assignment in a single geographic metropolitan area is considered temporary only if it is realistically expected to last—and actually lasts—for one year or less. The moment an assignment is expected to exceed 12 months, the physician's tax home legally shifts to the assignment location. From that exact date forward, all lodging and meal stipends become 100% taxable wages subject to immediate employment tax withholding.
Why is malpractice tail coverage escrow holdback legal on a paystub?
Tail coverage holdbacks are contractual deductions explicitly agreed upon in the master locum tenens service agreement. Because tail insurance policies (extended reporting endorsements) represent tens of thousands of dollars in contingent liability, staffing agreements permit agencies to withhold escrow reserves to ensure the physician completes the contracted coverage period. To remain compliant, the holdback must be explicitly itemized as a post-tax or escrow deduction on the settlement statement.
Are locum tenens doctors entitled to overtime under the Fair Labor Standards Act?
No. Under the Fair Labor Standards Act (FLSA), specifically 29 CFR § 541.304, licensed practicing physicians are explicitly exempt from both minimum wage and overtime requirements under the learned professional exemption. This exemption applies regardless of whether the doctor is paid a daily rate, hourly fee, or annual salary, provided they hold a valid license to practice medicine.
Can PayslipGen handle both 1099 settlement vouchers and W-2 paystubs in the same run?
Yes. PayslipGen allows you to maintain distinct company profiles and column mapping presets. You can process your 1099 contractor physicians with gross disbursement lines and zero tax withholding in one batch, and immediately process your W-2 clinical staff with FICA, Medicare, and federal withholding lines in another batch without paying additional fees or changing licenses.
Master Healthcare Staffing Payroll Without Cloud SaaS Tolls
Generate compliant, itemized locum tenens physician settlement vouchers directly from Excel. 100% offline, zero data leaks, one-time payment of $49 for lifetime access.
Get PayslipGen for $49 (Lifetime Access)Conclusion: Secure Clinical Operations with Local Sovereignty
Locum tenens physicians provide indispensable clinical expertise to healthcare facilities facing critical shortages. Managing their compensation demands equal rigor: strictly separating taxable clinical guarantees from non-taxable GSA travel per diems, maintaining accurate escrow accounting for malpractice tail insurance, and complying with IRS Accountable Plan standards.
By leveraging an organized Excel workflow paired with PayslipGen, medical staffing agencies and hospital clinics gain complete data sovereignty, eliminate recurring cloud SaaS tolls, and deliver audit-proof, password-encrypted settlement vouchers directly to their providers.
(Looking to streamline other clinical and specialized payroll workflows? Explore our detailed guides on Travel Nurse GSA Per Diem Stipends, Dental Hygienist Production Rates, or how to Generate 1099 Contractor Paystubs.)